In 2011 maps were the expensive, strategic asset you either owned or rented. Foundation models are the same, at a larger scale: what that means for dependency, pricing power and multi-sourcing.


In 2011 maps were the expensive, strategic asset you either owned or rented. Foundation models are the same, at a larger scale: what that means for dependency, pricing power and multi-sourcing.
In 2010 I argued that game mechanics must reward the behaviour you want. In AI products that test now separates engagement from manipulation, and regulators agree.

In 2011 I predicted Localicious would fail: copied features, a market already spoken for, and a company ignoring its own strength. AI wrappers and incumbents bolting on chatbots are repeating all three.
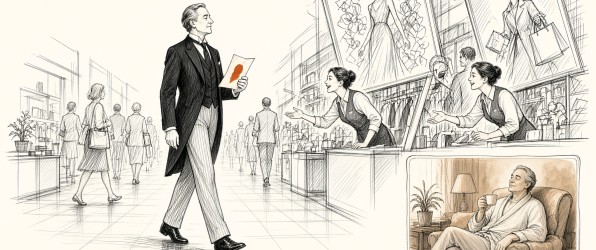
In 2012 online and offline retail merged around the customer. Now AI agents compare and shop on the customer’s behalf. Here is what brands and retailers should do.
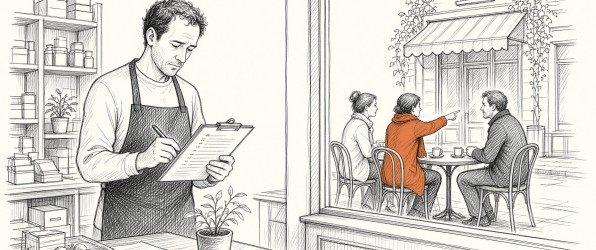
In 2012 I wrote about the location blind spot. In 2026 the bigger blind spot is the research your buyers do in AI assistants, which your analytics never see.

In 2011 I gave Foursquare and Facebook five lessons from Google+. The one that mattered was places data. In AI the question is the same: who owns your data layer?
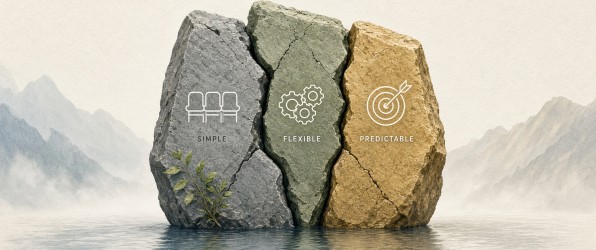
Simple, flexible, predictable: in 2011 the cloud forced software vendors to rebalance those three demands. AI pricing reopens the same trilemma, with seats, credits, outcomes and partners caught in between.

In 2003 a T-Mobile manager asked how to bill our buddy finder per minute. In 2026 software companies ask how to bill AI per token. What the telco story teaches about AI pricing.
Pricing AI features on tokens ties your revenue to the one input in your product that is getting cheaper fastest. Agents and customer-hosted models make it worse. Here is the two-layer alternative.

Brand safety tools can quietly defund whole publications. I asked ChatGPT what it thinks of centralised censorship, and the answer surprised me.